

By Nick Hoffmeyer, Head of Marketing at Bambi · Updated September 28, 2026 · 8 min read
Reviewed by Howard F. Berkowitz, a non-emergency medical transportation and paratransit expert with 30+ years in the industry (H&S Consulting).
You lower NEMT insurance costs mainly through three levers: telematics and dashcam programs that document safe driving, bundling policies with one carrier, and formal driver training programs, each of which gives an underwriter a reason to price you lower. Annual non-emergency medical transportation (NEMT) insurance costs can run anywhere from a few thousand dollars to well over $15,000 per vehicle depending on vehicle type, coverage, and location; this post covers how to bring that number down and manage the risk that drives it up in the first place. For carrier comparisons and current cost benchmarks by vehicle type, see our insurance provider review.
What Actually Lowers NEMT Insurance Premiums?
The fastest ways to lower NEMT insurance premiums are proving safe driving with data, consolidating policies with one insurer, and formally training drivers, since all three give an underwriter a concrete reason to price your risk lower than the default.
- Telematics / AI dashcams: Typical savings: Varies by carrier and program; What it requires: Hardware install, ongoing monitoring, driver buy-in
- Policy bundling (auto, general liability, workers' comp): Typical savings: Often meaningful; varies by carrier; What it requires: Consolidating with one carrier or broker
- Formal driver training (PASS, NEMTAC, similar): Typical savings: Varies by carrier; What it requires: Program fees per trainee, ongoing scheduling
- Paying annually vs. monthly: Typical savings: Avoids installment fees; What it requires: Cash flow to cover the annual premium upfront
Check savings percentages against your specific carrier's underwriting guidelines; discounts are carrier-dependent and not guaranteed industry-wide.
Telematics and Dashcams: Turning Driving Data Into a Discount
Telematics and AI dashcam systems record real driving behavior, harsh braking, tailgating, speeding, and give underwriters objective data instead of a self-reported safety claim. Some fleets using dashcam programs have reported meaningful combined savings on premiums and claims costs after implementation, though results vary by carrier and by how consistently the fleet acts on the coaching data the system produces. Ask the vendor or your carrier for current, documented results before counting on a specific savings number, since carrier discount programs change.
Beyond the insurance discount, this data has a second use: it's also useful defense against "crash for cash" style fraudulent claims, since footage removes ambiguity about what actually happened.
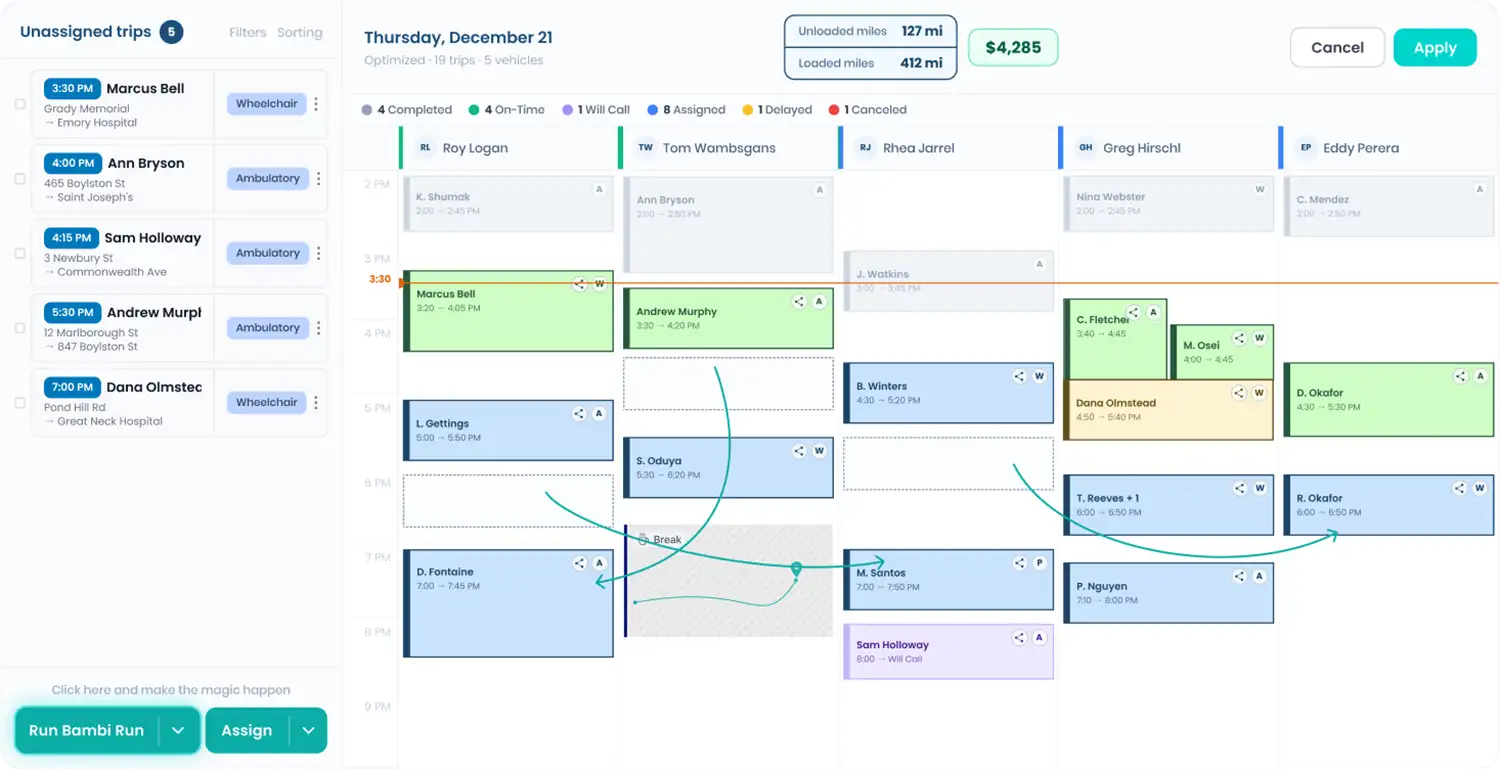
Route and dispatch software plays a supporting role here too. Fewer unnecessary miles and less idle time, which Bambi's Run Bambi Run scheduling helps with directly, means less driving exposure overall, which is itself a factor underwriters look at.
Bundling Policies for a Multi-Policy Discount
Combining commercial auto, general liability, workers' compensation, and cargo or passenger liability under one carrier often earns a multi-policy discount compared to buying each policy separately, and it simplifies claims handling since you're dealing with one carrier's process instead of several. Multi-policy customers also tend to stay with the same carrier longer, which gives the carrier an incentive to price the bundle competitively at renewal. Ask your broker for a bundled quote every renewal cycle, even if you've historically split policies across carriers.
Driver Training: The Underrated Lever
Formal driver training programs, the PASS (Passenger Assistance, Safety and Sensitivity) program from the Community Transportation Association of America is the best known, give underwriters a documented safety investment and, more importantly, actually reduce the incidents that drive claims. Ask each program for its per-driver fee; costs vary by program and format. Ask any training vendor for documented claims-reduction results, and ask your carrier which certifications they recognize for a rate credit, since not every carrier credits every program equally.
Managing Risk Day to Day
Lower premiums follow lower risk, and risk management is mostly a handful of unglamorous habits done consistently:
- Regular self-audits of driver records, incident reports, and vehicle maintenance logs, done before your renewal, not after a claim.
- Proactive fleet maintenance, including electronic driver vehicle inspection reports (DVIRs) where required, so a mechanical failure doesn't become a claim.
- Documented safety policies covering driver conduct, maintenance schedules, and incident reporting, since an insurer (and a broker credentialing you) will ask to see them, not just hear about them.
- Cybersecurity basics if you handle rider health information: encryption, multi-factor authentication, and role-based access. A HIPAA-covered NEMT provider that suffers a data breach faces both regulatory exposure and, increasingly, insurance implications. Check your HIPAA obligations with a compliance professional; this post is not legal advice.
Negotiating Your Renewal
When your policy renews, come to the conversation with your own safety and performance data rather than accepting the renewal rate as given. Track your operational costs (fuel, maintenance, wages, claims history) and your safety metrics (telematics scores, training completions, incident-free months) year-round so you have real numbers at renewal, not a general "we've been safe" claim. Working with an NEMT-specialist broker, rather than a generalist commercial auto agent, also tends to produce better outcomes since specialist brokers know which carriers actively want NEMT risk and which are pulling back from the category.
If what you actually need is help understanding payer reimbursement contract terms, filing deadlines, claim appeals, and rate clauses in a broker or MCO agreement, that's a different topic from insurance cost reduction; see our guide to winning and negotiating NEMT contracts instead.
FAQ
How much does NEMT insurance cost per vehicle? It varies widely by vehicle type, coverage limits, claims history, and location, with urban operations generally paying more than rural ones. See our insurance provider review for current cost ranges by vehicle type.
What's the fastest way to lower my NEMT insurance premium? Telematics or dashcam programs typically produce the quickest, most measurable discount since they give the underwriter objective driving data. Bundling policies with one carrier is a close second and requires less setup time.
Does driver training actually reduce insurance costs? It can, both directly through some carriers' training discounts and indirectly by reducing the incidents and claims that drive future renewal increases. Ask whether your specific carrier offers a training-based discount before budgeting for a program on that basis alone.
Should I pay my NEMT insurance annually or monthly? Paying annually usually avoids the installment or financing fees that monthly plans carry, if your cash flow allows for the larger upfront payment.
Is dispatch software actually connected to insurance costs? Indirectly, yes. Software that reduces deadhead miles and idle time lowers your overall driving exposure, one of the factors underwriters weigh, and gives you the trip data to support a renewal negotiation.
Run the numbers: the free NEMT insurance cost calculator turns your real quotes into a cost per vehicle, per trip and as a share of revenue.
Lower Risk, Lower Premiums, Fewer Headaches
Every lever in this post gets easier with better trip data behind it. Bambi's dispatch and scheduling tools track the trips, miles, and routes that back up a renewal negotiation or a telematics discount application. See pricing or book a demo to see it against your own fleet.
About the author: Nick Hoffmeyer is Head of Marketing at Bambi, the AI-powered dispatch and scheduling platform for non-emergency medical transportation (NEMT) providers. He works with NEMT owner-operators every day on growth, SEO, and the operational systems that help fleets run more trips with less stress. More from Nick: LinkedIn