[0:01] Nirav Chheda: a 45 to 60-day insurance quoting process down to 7 days?
[0:06] Nirav Chheda: That's correct. innovative guest with me today, Niko Fotopoulos, the co-founder of Sparx, uh, a gamechanging tech company that is helping NEMT businesses get insurance way faster than they usually would and cheaper.
[0:39] Nirav Chheda: Nico, how you doing? I'm doing well, Nirav.
[0:42] Niko Fotopoulos: Thanks for uhh having me on uh and excited to give a little insight on uh some questions that uh we've constantly seen NEMT operators ask.
[0:50] Niko Fotopoulos: a lot of things around why the rates are going up uh and some of the things that we're doing to uh uh combat Yeah, sounds good.
[0:59] Nirav Chheda: So, let's jump into topic number one.
[1:02] Nirav Chheda: There are changes in insurance rules from some of the big brokers like Modivcare that are getting instituted these days and um are catching NEMT businesses sort of blindsided.
[1:14] Nirav Chheda: Um can you talk to us about what's going on?
[1:18] Niko Fotopoulos: Yeah. So, I'll start with Modivcare just because we have partnerships with them in several of their larger state markets.
[1:24] Niko Fotopoulos: Um, and some of the things that we're seeing, uh, honestly, like you mentioned, take uh, uh, a lot of these operators by, um, uh, you know, just fully blindsided.
[1:34] Niko Fotopoulos: Um, so what we're seeing now, um, North Carolina is a great example.
[1:38] Niko Fotopoulos: um Modivcare has started to shut down operators that don't come in with uh what's called uh symbol 7 coverage uh for their autos.
[1:48] Niko Fotopoulos: Uh symbol 7 is uh their scheduled autos um which is a type of policy that covers when you give a list of all of your vans for um for your insurance.
[1:58] Niko Fotopoulos: It covers those specific vans. Um if you want to add vans during the year, it's a little bit of a painful process.
[2:04] Niko Fotopoulos: um if an employee accidentally uses their private car or private van for a transport just because that's all that was available um it doesn't cover that.
[2:14] Niko Fotopoulos: Um so it's a very limited version of um uh the you know more broad symbol 289 coverage that some operators may have been seeing recently um because the groups uh some of the larger groups like Motiveare are being
[2:29] Niko Fotopoulos: forced to switch over to that requirement.
[2:32] Niko Fotopoulos: Um, so I'll go into those in a second.
[2:34] Niko Fotopoulos: But what we're seeing, which becomes very tough, is that these transport brokers are not uh conveying this this new requirement quickly enough or clearly enough to these operators.
[2:45] Niko Fotopoulos: Um, so they end up renewing their their typical coverage, the thing they've had for past, you know, three, four, five years.
[2:52] Niko Fotopoulos: Um, and it leaves them uh fully non-compliant with Modivcare.
[2:56] Niko Fotopoulos: Um so folks come to us uh where Modivcare might be um 30 40 50% of their total rides um and they just got the note that um the renewed coverage they have no longer covers uh uh what
[3:10] Niko Fotopoulos: Modivcare needs it to.
[3:12] Niko Fotopoulos: So we've been working with a lot of groups on uh adjusting their coverage um sometimes even postrenewal um uh to be able to take on this symbol 289 coverage.
[3:23] Niko Fotopoulos: Um, and we've seen that now in a few markets where operators are again not being told upfront, not being given enough information, um, and it leaves them scrambling, um, uh, for for new coverage so that they can keep
[3:36] Niko Fotopoulos: taking rides. I've seen now multiple cases of, uh, operators who are out of business for uh, two weeks to a month just because they're waiting on uh, these insurance changes to take place.
[3:48] Niko Fotopoulos: Um whereas uh if they were um uh better told uh of these changes from their transport brokers uh they'd be in a far better spot rather than you know scrambling at the last minute.
[4:00] Niko Fotopoulos: Um so what we've been seeing there for those coverages switching from the symbol 7 which most folks have that's probably the most classical uh classic coverage uh in the space um to symbol 289 this more expanded coverage.
[4:15] Niko Fotopoulos: Um we've seen that mostly in the losses of the insurance market.
[4:19] Niko Fotopoulos: Um so uh markets like North Carolina that we've been looking at a lot.
[4:24] Niko Fotopoulos: Um uh there's been a um honestly an unheard of number of of claims and losses that have um come together in the past uh three or so years postcoid.
[4:35] Niko Fotopoulos: Um uh insurance largely is a lagging industry.
[4:39] Niko Fotopoulos: Um so what we see is that as the um uh these claims total um the insurance market follows behind it.
[4:48] Niko Fotopoulos: Um so three or four years after all these claims come about the insurance market then catches up and starts to impose these uh um these rate increases these new requested coverages to the um uh the trickle down parts
[5:02] Niko Fotopoulos: of the market. Um so as insurance as a market gets harder we then see the uh operators of the market also now have to deliver that bad news to to their operators in the space.
[5:14] Niko Fotopoulos: Um so the what we've seen um uh through the claims of the past 3 four years is that Modivcare has um experienced um either lawsuits themselves or their operators who have been doing a lot of rides
[5:26] Niko Fotopoulos: for them have experienced really serious lawsuits um that have put them out of business for larger periods of time.
[5:33] Niko Fotopoulos: um because they were on this symbol seven coverage.
[5:36] Niko Fotopoulos: Um Modivcare this year has um or sorry Modivcare late last year um has now instituted this new more uh comprehensive coverage uh requirement so that more of their operators are covered more consistently uh and
[5:50] Niko Fotopoulos: it's more in line with what we've seen um for losses in the North Carolina market.
[5:55] Niko Fotopoulos: Um just as that using that as the example.
[5:58] Niko Fotopoulos: Um so to uh to give operators even like a little bit of an explanation because many folks don't when they just say here's the new requirements now go figure it out.
[6:07] Niko Fotopoulos: Um uh Modivcare um having seen their operators and themselves not be more heavily covered uh after seeing crazy number of claims in the last two years um uh they now are looking to expand the protection that
[6:23] Niko Fotopoulos: they and their operators are getting uh from their markets.
[6:27] Niko Fotopoulos: Um, so that's what we've been seeing on that end that has been honestly very very uh tough for the operators.
[6:35] Niko Fotopoulos: Um, and something that we've been helping a lot of folks um take on um after having again issues uh uh getting this like very specific type of coverage all of a sudden um versus the coverage they've had the
[6:47] Niko Fotopoulos: past four four years or so.
[6:50] Nirav Chheda: Yeah. So on that last point, Nico, like let's say I'm an NEMT business.
[6:55] Nirav Chheda: I've been operating for some years.
[6:56] Nirav Chheda: I had no idea that there are all these changes in insurance rules coming about that are going to affect me like how can I get ahead of it?
[7:05] Niko Fotopoulos: Yes. So, one thing we've seen that's been successful for operators is that if they have been uh more proactive in working with their transport brokers and keeping up with uh requirement changes.
[7:17] Niko Fotopoulos: Um they have been more successful in seeing when those changes come into place.
[7:22] Niko Fotopoulos: Um so each of these transport broker groups have a compliance team um that um we highly encourage our um our insureds to keep in contact with um regularly check in maybe once or twice a year on any general
[7:37] Niko Fotopoulos: compliance changes that may be being pushed out so that it doesn't catch them by surprise when um there might be a renewal uh for that following year.
[7:46] Niko Fotopoulos: Um, I think that's been the best practice that we've seen in order to keep folks compliant with um uh with their groups there.
[7:53] Nirav Chheda: Okay, cool. Thanks for sharing. I want to move to topic number two now, which is, you know, ride share and TNC's.
[8:03] Nirav Chheda: How is this affecting the NEMT industry?
[8:07] Nirav Chheda: Um, you know, people always hear about, oh, is Uber or Lyft getting into NEMT?
[8:12] Nirav Chheda: You know, what's going on with that?
[8:14] Niko Fotopoulos: Yeah. So it's very interesting. Um as you mentioned Uber and Lyft are entering the market and I know a lot of operators have seen this happen where these behemoth companies come in.
[8:25] Niko Fotopoulos: They think they'll do a really great job and reality is the uh the operators have always been far and better uh performing uh uh compared to some of these larger groups that are just doing this for the first
[8:36] Niko Fotopoulos: time. Um, so what we've been seeing, again, insurance trend-wise, um, it's been really crazy.
[8:43] Niko Fotopoulos: The last 12 years of the the commercial auto insurance market, um, there's never been an upyear.
[8:50] Niko Fotopoulos: Um, uh, insurance companies have lost money on commercial auto insurance.
[8:55] Niko Fotopoulos: The past 12 years, except during COVID, uh, when there were no one there was no one on the road to, uh, to have an accident.
[9:02] Niko Fotopoulos: Um what we've seen in the past four years is that ride share um has introduced now um uh one point something like 1.5 to 2x the claims um uh in their severity because um there's more uh more more
[9:17] Niko Fotopoulos: vehicles on the road for businesses um and there's also um more exposure to random risks.
[9:23] Niko Fotopoulos: You're now taking random people into your van and moving them around.
[9:26] Niko Fotopoulos: Um so what we've seen is that ride share has made the market even worse.
[9:30] Niko Fotopoulos: Um, and it's left insurance companies cutting these types of businesses out of their coverage.
[9:35] Niko Fotopoulos: Um, and has also left any NEMT operators that may do this in as a an additional part of their business um, uh, totally stunted on their insurance.
[9:44] Niko Fotopoulos: Um, so we've seen a lot of insurance companies now raise rates for um, any NEMT operators that may be adding that as a service just because Uber and Lyft have sort of ruined the insurance market for anyone that
[9:56] Niko Fotopoulos: is involved with that as a business.
[9:58] Niko Fotopoulos: It's also resulted in higher rates for folks who are not offering that just because these these ride share services have now increased the riskiness of commercial auto uh in the past few years.
[10:10] Niko Fotopoulos: Um so the trend has hit operators harder than um than what we expected generally.
[10:17] Niko Fotopoulos: Um but I think that actually will adjust down in the next 3 or four years now that um we're generally cutting ride share out of the uh the coverable uh equation for a lot of these insurance companies.
[10:29] Nirav Chheda: Okay. Well, give me some silver lining here, Nico.
[10:32] Nirav Chheda: Like Uber andyft, I mean, what do you think is going to be the future of their sort of efforts to get into NEMT at this point?
[10:40] Niko Fotopoulos: You know what's funny? I've actually um talking to the teams there um I've seen that there's opportunities for them to become more and more of these uh transport brokers purely.
[10:52] Niko Fotopoulos: Um so continually partnering with operators uh to bring more rides to them.
[10:57] Niko Fotopoulos: Um I'm not 100% sure where the uh uh the movement will go if it's going to continually be bringing um uh uh you know the internal Uber network more rides.
[11:09] Niko Fotopoulos: Um so folks who are just members of Uber there.
[11:12] Niko Fotopoulos: Um or opening up that more to more operators.
[11:15] Niko Fotopoulos: Um but I think the end outcome in the next few years will be Uber being another potential uh revenue source for operators.
[11:22] Niko Fotopoulos: Um and also now um as ride share and NEMT obviously continue to separate um having less and less of an impact on their insurance coverage Interesting.
[11:34] Nirav Chheda: Interesting. All right. Well, let's let's move on to topic number three.
[11:39] Nirav Chheda: Why are insurance premiums going higher for N&T businesses?
[11:44] Nirav Chheda: And you know, obviously it's happening in some regions and areas across the country more than others.
[11:51] Nirav Chheda: Um, but in general, like what's what's going on there?
[11:55] Nirav Chheda: Like like especially the places where, you know, in recent times, in the past year, even insurance premiums have really spiked up year-over-year.
[12:04] Nirav Chheda: Like what's going on there? Yeah.
[12:06] Niko Fotopoulos: So like I had mentioned um uh commercial auto insurance has never seen a positive year.
[12:13] Niko Fotopoulos: Um the insurance carriers have lost money on giving commercial auto as a coverage uh for the past 12 years and it's only gotten worse.
[12:22] Niko Fotopoulos: Um the only positive year was during COVID when there were no rides being done.
[12:27] Niko Fotopoulos: Uh there was no really no one on the road.
[12:30] Niko Fotopoulos: Um so much much harder market uh the past few years.
[12:34] Niko Fotopoulos: Um what we've seen now is that along with industries like um the uh the property insurance industry um uh where storms have continually led to losses in the insurance market.
[12:47] Niko Fotopoulos: A lot of insurance has become destabilized.
[12:50] Niko Fotopoulos: Um and so the insurance companies are uh looking for ways to counteract that.
[12:56] Niko Fotopoulos: Principal ways to raise rates. Um how can we survive some of the harder years in insurance?
[13:01] Niko Fotopoulos: We'll charge our customers more. um which puts operators obviously in a tough spot because they're now forced to figure out the best way of uh decreasing their rates in the market.
[13:13] Niko Fotopoulos: Um and the best way to do that is to be less risky as a business.
[13:17] Niko Fotopoulos: Um so what we've been working with folks on and some of the um the things that we've been developing on our end um what we've done is start partnering with our carriers um so the insurance companies that offer
[13:29] Niko Fotopoulos: these products. um we've been bringing uh uh software solutions to them where we can say hey these are things that are uh making our customers less risky um and giving them the opportunity to uh uh keep their rates
[13:44] Niko Fotopoulos: low for longer periods of time.
[13:46] Niko Fotopoulos: Um so one thing that um we've seen as a really interesting trend right now to try and keep those rates low are bringing solutions like Bambi to these insurance partners um uh with the idea that with for example
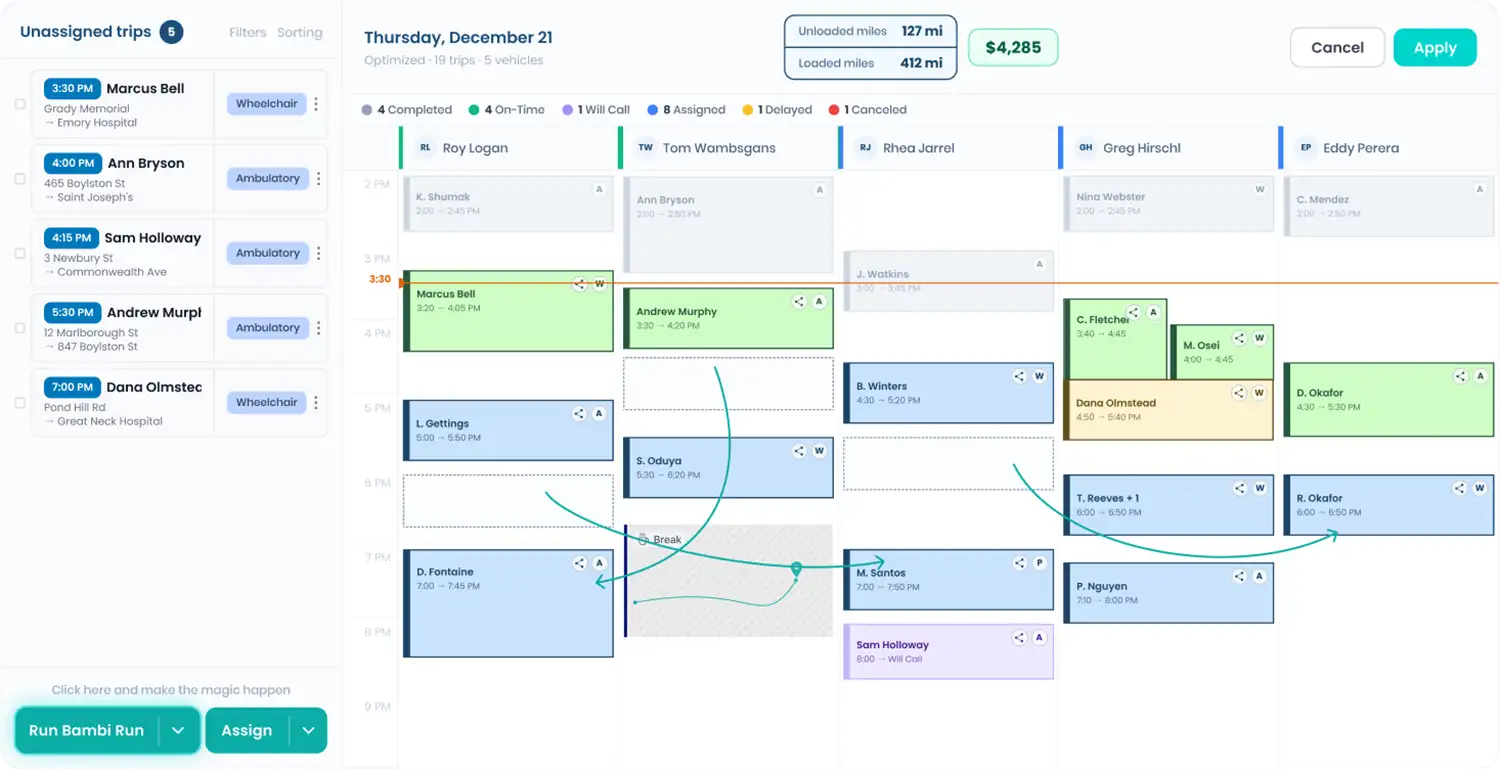
[13:57] Niko Fotopoulos: scheduling um if we're doing that correctly and consistently that's something that reduces a lot of the risk of these businesses um and is something that um uh talking to our insurance partners there's a real opportunity to keep rates
[14:09] Niko Fotopoulos: consistently low for uh parties that are adopting um uh tech like Bambi in their everyday operations.
[14:16] Niko Fotopoulos: Um, so something that we see as the best way to fight against these rising rates.
[14:22] Niko Fotopoulos: And we've seen it now too.
[14:23] Niko Fotopoulos: I think a lot of people talk about telematics as the um uh the holy grail of a lot of this.
[14:29] Niko Fotopoulos: Um so adding cameras into cars um and then the continual steps to take on the software side will only keep rates lower for the operators that take the time to do it.
[14:39] Niko Fotopoulos: So that's what we're hoping to see more of in the market as things just get harder.
[14:43] Niko Fotopoulos: Generally the folks who take the time to adopt really great tech to uh make themselves less risky will see the benefits of lower rates.
[14:50] Nirav Chheda: And can you explain Sparx in general?
[14:54] Nirav Chheda: Like how did you found the company?
[14:57] Nirav Chheda: What is you know what is your guys' secret sauce about how you're getting insurance to NEMT providers so fast?
[15:05] Niko Fotopoulos: Yes. So the the quick pitch on Sparx um we are a tech enabled insurance brokerage.
[15:12] Niko Fotopoulos: Um we solely focus on the medical space, namely medical transportation and medical malpractice.
[15:18] Niko Fotopoulos: Um and what we've done on our inside um we've automated almost every part of the insurance shopping process.
[15:25] Niko Fotopoulos: Um so we take our expert insurance brokers um on our team who um were ex operators and a lot of these businesses um and we pair them with our platform that takes the applications for these businesses and shops
[15:38] Niko Fotopoulos: them across 150 carriers automatically. So we send it out to every part of the market we can and then we get back as many quotes as we can.
[15:46] Niko Fotopoulos: Um and that's where we can present the best options to um uh to our market uh to be able to uh bring the best coverage at the best rates for uh for operators of these medical businesses.
[15:58] Niko Fotopoulos: Um, so that's our main goal really at the end of the day is to uh move quickly for customers um and make sure that we're exhausting every option in the market.
[16:07] Niko Fotopoulos: Um, and then continually move towards this future where we can partner fully with our insurance company partners and start offering ways that these uh operators can keep their rates low by bringing in interesting technology, interesting software also makes
[16:23] Niko Fotopoulos: their lives easier. So that's the that's how we've designed our system and hope to continue to push there.
[16:28] Niko Fotopoulos: When it comes to the hard numbers, um what we've seen most folks experience is a 45 to 60day um uh quoting process.
[16:37] Niko Fotopoulos: So a mixture of uh different applications um uh different um uh uh pieces of information they need to pull together from all these different sources.
[16:46] Niko Fotopoulos: Um so what we've designed is a streamlined quoting process that takes someone 10 minutes to pull together.
[16:53] Niko Fotopoulos: um and we can produce quotes uh from our different carrier partners uh within uh 7 days.
[16:59] Niko Fotopoulos: Um so that's the benchmark that we reach for is a oneweek turnaround on the most expensive, most comprehensive coverage that they usually experience, but giving it, you know, uh cost- effective and quickly um to keep their business So
[17:14] Nirav Chheda: you're telling me that you've turned a 45 to 60day insurance quoting process down to seven days?
[17:20] Niko Fotopoulos: That's correct. Not bad. Yeah. Right.
[17:24] Niko Fotopoulos: We do our best. Um and then what we see on the premium savings side too, um uh it's different for you know different types of businesses, but I think generally speaking um uh we've seen folks end up with
[17:36] Niko Fotopoulos: quotes anywhere from uh uh 10k to uh I mean on the top end 20k per vehicle.
[17:42] Niko Fotopoulos: Um and so a lot of our partners come in around 5k per vehicle.
[17:46] Niko Fotopoulos: Um for a lot of that more comprehensive coverage that uh groups like Modivcare are requiring.
[17:52] Niko Fotopoulos: Um for the more basic coverage at the Symble 7, which we hope more of the market hits, um we come down as low as 2K per vehicle.
[17:59] Niko Fotopoulos: Um so that's that's where we benchmark and hope to keep operators very cheaply covered um across the board.
[18:06] Nirav Chheda: So, are you telling me that you're reducing insurance premiums for NEMT businesses by roughly 75%.
[18:14] Niko Fotopoulos: On average, that's the that's the plan is for folks that we can deeply partner with um and uh put them on some of our suggested ways of reducing the risk of their business.
[18:24] Niko Fotopoulos: Um we see we see premiums drastically fall.
[18:29] Niko Fotopoulos: This sounds pretty gamechanging. So that's the that's the hope uh is to continue to work with folks on again keeping them covered long term and cheaply.
[18:39] Nirav Chheda: So Nico, can you share with me some stories of NEMT businesses that you've worked with where you know their insurance policy was out of date for the broker they're working with, their premiums are going up.
[18:53] Nirav Chheda: You and Sparx came in and turned things around for them.
[18:57] Niko Fotopoulos: Yeah. So, one group we worked with recently um they had just come from again Modivcare um and they had a policy that um uh was uh uh recently expired um two or three days before they reached
[19:10] Niko Fotopoulos: out to us um only because they had gone to Modivcare and they received the unfortunate news that um there was nothing they could do.
[19:19] Niko Fotopoulos: It was uh out of compliance.
[19:21] Niko Fotopoulos: Um they needed to go find some new coverage.
[19:23] Niko Fotopoulos: Um so they referred them to us uh since we're preferred partner for them.
[19:27] Niko Fotopoulos: um uh again in several of their states.
[19:30] Niko Fotopoulos: Um when they started working with us, um what we were able to do was turn around a quote within three days um to get them back up and running back again within 3 days.
[19:39] Niko Fotopoulos: Um so something where um a normal broker would have kept them out of business with Modivcare um for anywhere from a month to two months.
[19:47] Niko Fotopoulos: Um so something that um we were able to turn something around incredibly quickly um to get them uh back on the road.
[19:54] Niko Fotopoulos: Um, and that's what we really prioritize is making sure that our operators are not stressed about insurance.
[20:00] Niko Fotopoulos: Um, but instead are worried about bringing great service to patients and uh, keeping their drivers on the road uh, and serving great customers.
[20:08] Nirav Chheda: So, I love it. You guys are really making a big impact in this industry, making it viable for NEMT businesses to operate profitably.
[20:20] Nirav Chheda: Um, for everyone watching, I'm putting the contact info of Sparx in the description of this video.
[20:27] Niko Fotopoulos: Um, Nico, what is the best way for NEMT businesses to get in touch with you Yeah, so we'll include the uh uh my teammates's email um uh Ryan, who is the um the head of our practice um focusing
[20:40] Niko Fotopoulos: on uh medical transport. Um and then also include my personal cell um uh so feel free to give me a call or a text uh for any needs that come up.
[20:50] Nirav Chheda: Nico, thanks so much. Run, Bambi, run.